Your nonprofit has an annual budget. The board approved it. Everyone agreed on the plan.
Three months later, how do you know whether things are going according to that plan?
Maybe donations are coming in more slowly than expected. Maybe payroll costs are higher than anticipated. Or perhaps a program is spending less than budgeted—but only because you haven’t been able to fill an important position.
This is where budget-to-actual reporting becomes one of the most valuable tools in nonprofit financial management.
It helps to think of your nonprofit’s budget as a roadmap. It shows where your organization plans to go, how much funding you expect to have, and how you intend to use those resources.
Your budget-to-actual report tells you whether you’re following that route—or whether something has changed along the way.
The earlier you spot a change, the more ways you can respond.
At Bay Business Group, we help nonprofit leaders and boards turn financial reports into practical insights through our outsourced accounting, fractional controller services, and fractional CFO support services.
As you’re considering your nonprofit’s budget, read on for how budget-to-actual reporting can help you understand your organization’s financial performance, make better decisions, and keep your board informed without creating unnecessary alarm.
What Is Budget-to-Actual Reporting for Nonprofits?
Budget-to-actual reporting is exactly what it sounds like.
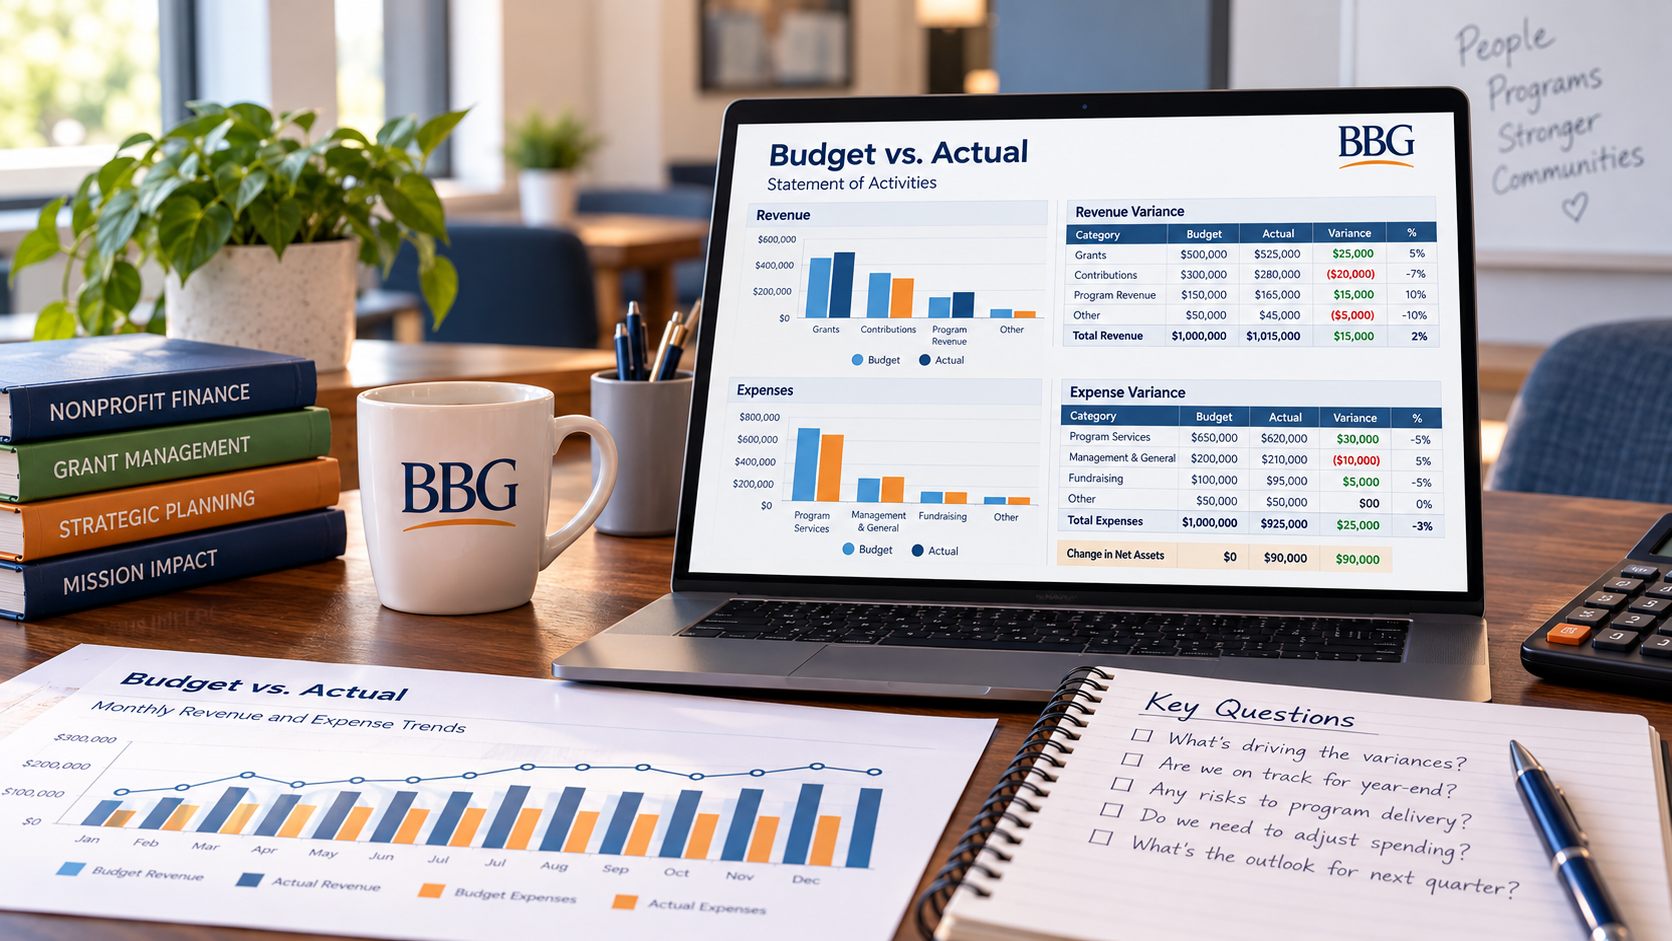
It compares what your nonprofit planned to receive and spend with what it actually recorded during a particular period.
The difference between the two is called a variance.
For example, suppose your organization expected to receive $100,000 in donations during the first quarter, but actual donations totaled $85,000.
You’re $15,000 below budget. That difference is a variance.
But here’s the important part: The variance itself isn’t the whole story. It’s the beginning of a conversation.
Why are donations below budget? Did a major donor decide not to contribute? Is a fundraising event scheduled later than originally planned? Or is the funding still expected, just arriving later?
Each explanation could lead to a different management decision.
Budget-to-actual reporting helps you move beyond identifying differences to understanding what those differences mean.
Why Your Board Needs Budget-to-Actual Reports
Your board approves the annual budget because it represents the organization’s financial plan for carrying out its mission. The budget establishes expectations about revenue, expenses, programs, staffing, and other priorities.
But approval is only the beginning. The board also needs to understand whether the organization is progressing according to that plan. That’s where budget-to-actual reporting comes in.
Think of it this way:
The annual budget shows the board the route. Budget-to-actual reporting shows whether the organization is staying on course.
A good report should help the board see:
- Whether revenue is meeting expectations
- Whether expenses are staying within the financial plan
- Whether programs are operating as anticipated
- Whether significant financial assumptions have changed
- Whether leadership is responding appropriately to new information
It also helps the executive director demonstrate responsible financial oversight.
Instead of simply reporting that the organization spent $50,000 last month, you can explain whether that spending was expected, why it occurred, and whether it changes the outlook for the year.
7 Steps for Assessing Variance
Step 1: Start With a Good Annual Budget That’s Broken Down Monthly
Before you can measure whether your nonprofit is on track, you need a realistic plan to measure against. That starts with an annual budget.
But an annual total isn’t enough. For meaningful budget-to-actual reporting, your nonprofit should also break the budget down by month.
Why Monthly Budgets Matter
Imagine your organization expects to receive $1.2 million in annual revenue. You could simply divide that number by 12 and assume $100,000 will come in each month.
But that’s probably not how your funding actually works.
Perhaps:
- A major fundraising event happens in November.
- A foundation grant supports a program beginning in July.
- Individual donations increase near year-end.
- Government grant reimbursements arrive after expenses are incurred.
- Membership revenue is concentrated around annual renewals.
If you divide annual revenue evenly across 12 months, your monthly budget-to-actual reports may show misleading variances. You could appear significantly behind budget in March even though the organization is performing exactly as expected.
A more useful monthly budget reflects when revenue is expected to be recognized and when expenses are expected to occur, using assumptions consistent with the organization’s accounting and reporting approach.
The timing of cash receipts is a separate question that belongs in the cash flow forecast.
What Should Be Included in a Monthly Budget?
At a minimum, your monthly budget should reflect:
- Expected revenue by major funding source
- Personnel costs
- Program expenses
- Fundraising expenses
- Administrative and operating costs
- Significant one-time or seasonal expenses
For nonprofits managing multiple grants or programs, additional details may be necessary. While the goal isn’t to create the most complicated spreadsheet possible, you want to establish realistic expectations that can be compared with actual financial results.
Read More: How to Prepare Your Nonprofit’s Annual Budget.
Step 2: Learn How to Read a Budget-to-Actual Report
A basic budget-to-actual report usually includes three columns:
- Budget: What you expected.
- Actual: What happened.
- Variance: The difference between the two.
Here’s a simplified example.
Example: A Nonprofit’s Monthly Budget-to-Actual Report
| Category | Budget | Actual | Variance |
| Contributions | $50,000 | $40,000 | ($10,000) |
| Grant revenue | $75,000 | $75,000 | $0 |
| Program revenue | $25,000 | $30,000 | $5,000 |
| Total revenue | $150,000 | $145,000 | ($5,000) |
| Personnel expenses | $90,000 | $95,000 | ($5,000) |
| Program expenses | $35,000 | $30,000 | $5,000 |
| Administrative expenses | $15,000 | $17,000 | ($2,000) |
| Total expenses | $140,000 | $142,000 | ($2,000) |
| Operating surplus | $10,000 | $3,000 | ($7,000) |
Illustrative example. Favorable and unfavorable variances are presented based on their impact on the operating result: higher revenue and lower expenses are favorable; lower revenue and higher expenses are unfavorable.
This report tells us the organization expected a $10,000 surplus but actually generated a $3,000 surplus. That’s a $7,000 unfavorable difference.
But that doesn’t automatically mean something is wrong. We first need to understand the reason for the variance.
Look at the program expenses. The organization spent $5,000 less than budgeted. While that looks favorable, we need to consider if the savings occurred because a program was delayed? Or because an important staff position remained vacant?
The organization may have spent less money, but it also may have delivered fewer services than planned.
Now look at personnel expenses. The organization spent $5,000 more than expected. That appears unfavorable.
But what if the additional cost came from hiring temporary staff to support an unexpected increase in program demand?
The spending might be reasonable—or even beneficial—depending on the circumstances.
A favorable variance isn’t always good news. And an unfavorable variance isn’t always bad news. The real question is what caused the difference and whether leadership needs to respond.
Step 3: Look for Trends, Not Just One-Month Differences
One month of unexpected results doesn’t necessarily mean your nonprofit is headed in the wrong direction.
But repeated variances can signal a developing problem.
For example, suppose your organization budgets $40,000 in monthly individual contributions.
Here’s what happens over four months:
| Month | Budget | Actual | Monthly variance |
| January | $40,000 | $38,000 | ($2,000) |
| February | $40,000 | $35,000 | ($5,000) |
| March | $40,000 | $32,000 | ($8,000) |
| April | $40,000 | $30,000 | ($10,000) |
| Total | $160,000 | $135,000 | ($25,000) |
In January, the difference was relatively small.
By April, the monthly shortfall had increased to $10,000, and the organization was $25,000 behind its cumulative contribution budget.
That’s a trend worth investigating. Maybe a major donor hasn’t renewed, or a fundraising campaign is underperforming. Perhaps the budget assumptions were too optimistic.
Whatever the cause, identifying the trend in April gives leadership far more time to respond than discovering the problem in November.
Review Monthly and Year-to-Date Results
For most nonprofit leaders, it’s helpful to review both:
Monthly results ask what happened during the most recent month?
Year-to-date results ask how are we performing against the budget since the beginning of the fiscal year?
The monthly view can highlight new developments. The year-to-date view helps distinguish temporary fluctuations from larger patterns.
Step 4: Ask Why Before Deciding What to Do
When you identify a significant variance, resist the temptation to jump immediately to a solution. Start by understanding the cause.
Suppose your nonprofit’s grant revenue is $75,000 below budget. Before making changes, ask:
- Was the grant awarded?
- Is the revenue expected to be recognized later?
- Were conditions for recognizing the grant not yet met?
- Did the grant period or program schedule change?
- Was the original budget based on an award that wasn’t guaranteed?
- Has the funding opportunity been lost?
These possibilities have very different implications.
If the revenue is simply expected later, the annual financial outlook may still be reasonable. If the grant was denied, leadership may need to reconsider the spending it was expected to support. If the issue involves reimbursement timing rather than revenue recognition, the concern may be primarily about cash flow.
For contributions and grants, the accounting treatment depends on the agreement. ASC 958-605 governs contributions, including the evaluation of conditions and donor restrictions, while qualifying exchange transactions are addressed under ASC 606.
As an executive director, you don’t need to memorize those standards. An accounting partner can explain why a number appears—or doesn’t appear—in your financial reports.
The most useful question you can ask when reviewing a variance is: “Is this a timing difference, a change in expectations, or a problem we need to address?”
Step 5: Use Variances to Make Decisions While You Still Have Options
This is where budget-to-actual reporting moves beyond financial reporting into a leadership tool.
Let’s say your organization planned to launch a new community program in September, but by June, fundraising revenue is running significantly below expectations.
You now have to decide if you move forward with the program as planned?
Delay the launch? Reduce the scope? Increase fundraising efforts? Seek a new grant or sponsorship?
Because you’ve been reviewing financial results monthly, you have time to evaluate those options before making major commitments.
What Can You Do When Revenue Is Below Budget?
Depending on the situation, leadership might:
- Increase attention to fundraising
- Reach out to major donors
- Pursue additional grant opportunities
- Delay discretionary spending
- Postpone a planned hire
- Phase in a program expansion
- Revisit assumptions about expected revenue
- Update the cash flow forecast
The right response depends on the size, cause, and expected duration of the shortfall. A temporary timing difference may require monitoring rather than immediate spending cuts. A permanent loss of funding may require more significant action.
What If Expenses Are Above Budget?
Start by understanding why costs are increasing.
Are prices higher than expected? Has program demand grown? Are staffing costs exceeding projections? Did the organization incur an unusual one-time expense?
Once you understand the cause, evaluate whether the additional spending is justified and how it affects the remaining year.
The goal isn’t to eliminate every variance. It’s to make sure spending decisions remain aligned with your organization’s resources and priorities.
Read More: Understanding Your Program’s True Costs
Sometimes the Best Decision Is to Pause
Nonprofit leaders are often eager to move important projects forward.
That’s understandable. There’s a mission to accomplish and a community to serve.
But sometimes the most responsible decision is to delay an initiative until the funding picture becomes clearer. Monthly budget-to-actual reporting gives you the opportunity to make that decision proactively instead of waiting until cash becomes tight.
Step 6: Know When to Bring the Board Into the Conversation
One of the trickiest questions for an executive director is:
When should I tell the board we’re off budget?
You don’t want to raise unnecessary concern every time a number differs from the budget. But you also don’t want board members to discover a significant financial problem after leadership has already exhausted its options.
The key is to distinguish routine variances from material changes that could affect the organization’s financial plan.
Not Every Variance Requires a Special Board Meeting
Some differences are normal. For example, a vendor invoice may arrive a month later than expected. A fundraising event may generate slightly more or less revenue than planned. A planned hire may begin several weeks later than anticipated. These items may be appropriate to address through regular monthly financial reporting.
Our accounting team can help you determine whether they are temporary, recurring, or significant enough to warrant additional attention.
When Should the Board Be Involved?
Consider involving the board or finance committee when:
- A major funding source is lost or becomes significantly uncertain
- The organization expects a material annual deficit that wasn’t previously approved
- Available operating reserves may fall below an established target or policy
- A significant program or staffing change is being considered
- Cash flow projections indicate potential difficulty meeting obligations
- Leadership needs approval for material changes to the financial plan
- A major financial risk could affect the organization’s ability to fulfill its mission
The specific reporting and approval thresholds should reflect your organization’s governance policies and financial circumstances.
When communicating with your board, you don’t want to cause unnecessary alarm. The best approach is to be factual, timely, and prepared.
Rather than saying:
“We’re $100,000 behind budget, and we’re worried.”
Try:
“We’re currently $100,000 below our year-to-date revenue budget, primarily because a major grant renewal hasn’t been confirmed. We’ve reviewed the potential impact, identified expenses that could be delayed, and updated our forecast. We’d like to discuss the options with the finance committee.”
The second explanation provides context, demonstrates that leadership is responding, and invites the board into a productive conversation.
The goal isn’t to surprise the board with bad news. It’s to give board members enough information to help the organization make good decisions.
And in some cases, board members may be part of the solution. They may be able to support donor stewardship, assist with fundraising introductions, or help leadership evaluate strategic trade-offs.
Proactive communication builds trust. Waiting until a financial concern becomes a crisis usually makes the conversation harder.
Read More: How to Present Your Budget to the Board of Directors.
Step 7: Update Your Forecast When the Original Plan No Longer Reflects Reality
Your board-approved budget remains an important reference point throughout the year. But it was developed using the information available at the time. What happens when circumstances change significantly?
Suppose your organization budgeted $2 million in annual revenue, but halfway through the year a major $300,000 grant is denied.
You shouldn’t pretend the original revenue expectation is still realistic. That’s when reforecasting becomes important.
Budget vs. Reforecast: What’s the Difference?
Your budget represents the original approved financial plan.
Your reforecast updates expectations based on what leadership knows today.
For example:
| Financial measure | Approved budget | Updated forecast |
| Annual revenue | $2,000,000 | $1,700,000 |
| Annual expenses | $1,950,000 | $1,800,000 |
| Annual surplus / (deficit) | $50,000 | ($100,000) |
The updated forecast reflects both the lost funding and management’s planned $150,000 expense reduction.
It also shows that additional decisions may be needed to address the remaining $100,000 deficit.
That doesn’t mean the original budget should be erased. Keep it as the benchmark for understanding what changed.
The forecast helps leadership plan the remainder of the year.
How Often Should You Reforecast?
Many nonprofits benefit from quarterly reforecasting, with additional updates when significant events occur.
For example:
- A major grant is awarded or denied
- Fundraising results change materially
- Staffing plans shift
- Program expenses increase significantly
- A new initiative is approved
- Cash flow expectations change
Reforecasting helps leadership move from explaining past differences to making decisions about the future.
What Should an Executive Director Review Each Month?
You don’t need to spend hours examining every account. Instead, develop a consistent monthly financial review process.
Here are seven questions to ask your accounting team:
- Are we ahead of or behind our revenue budget? Which funding sources are driving the difference?
- Are expenses higher or lower than expected? Are the differences temporary or likely to continue?
- Are any programs or grants materially off budget? What does that mean for program delivery and funding requirements?
- Are there significant year-to-date trends? Are variances getting larger or resolving?
- How does this affect our cash position? Do we have sufficient available cash to meet upcoming obligations?
- Do we need to adjust our forecast or plans? Are there decisions we should make now?
- Does the board need to know or take action? Is the issue significant enough to affect oversight, strategy, or previously approved plans?
These questions can turn a monthly finance meeting into a much more productive conversation.
Read More: Financial Questions Every Nonprofit Executive Director Should Ask
Download Bay Business Group’s Monthly Budget Review Checklist
Common Budget-to-Actual Reporting Mistakes to Avoid
Even organizations that prepare regular financial reports can miss opportunities to use them effectively.
Here are some common mistakes.
Comparing actual results with an unrealistic monthly budget. If your funding is seasonal or tied to grant activity, an evenly divided annual budget may create misleading variances.
Focusing only on expenses. Revenue shortfalls can have a greater impact on financial sustainability than relatively small expense differences.
Assuming every favorable variance is good. Underspending may indicate delayed programs, staffing vacancies, or activities that haven’t occurred.
Looking only at the current month. Year-to-date results and trends often reveal more than a single reporting period.
Ignoring the difference between revenue and cash. An organization can be on budget for revenue and still face cash flow challenges.
Explaining variances without taking action. Understanding what happened is important, but the real value comes from deciding what to do next.
Waiting too long to communicate material concerns. Boards need timely information about significant changes, along with management’s assessment and proposed response.
Frequently Asked Questions About Nonprofit Budget-to-Actual Reporting
What is a budget-to-actual report?
A budget-to-actual report compares an organization’s planned revenue and expenses with its actual financial results. It highlights differences, called variances, so leadership can understand financial performance and determine whether adjustments are needed.
What is a budget variance?
A budget variance is the difference between a budgeted amount and the actual result. Variances can be favorable or unfavorable, but their significance depends on the cause and financial impact.
How often should nonprofits review budget-to-actual reports?
Monthly reviews are a useful practice for many nonprofits. They allow leadership to identify significant changes early enough to respond before problems become more difficult to manage.
Does being over budget always mean something is wrong?
No. Higher spending may reflect increased program activity, unexpected demand, or other legitimate circumstances. The important question is whether the expense is justified, appropriately funded, and consistent with organizational priorities.
When should an executive director notify the board about a budget variance?
Routine variances can generally be discussed through regular financial reporting. Significant changes that affect funding, liquidity, reserves, program commitments, or the approved financial plan may warrant earlier communication with the board or finance committee.
What’s the difference between budget-to-actual reporting and cash flow forecasting?
Budget-to-actual reporting compares planned financial results with what has already happened. Cash flow forecasting estimates future cash receipts and payments. Both help leadership understand financial performance and anticipate potential challenges.
Read More: Cash Flow Management for Nonprofits
How Bay Business Group Helps Nonprofits Turn Financial Reports Into Better Decisions
Budget-to-actual reporting is only useful when the information is accurate, timely, and understandable. If your nonprofit receives financial statements weeks after the month ends—or reports that are difficult to interpret—leadership may miss opportunities to respond to changing circumstances.
At Bay Business Group, we help nonprofit leaders and boards move beyond simply receiving financial reports.
Through our outsourced accounting, fractional controller, and fractional CFO services, we support:
- Accurate, timely monthly financial reporting
- Budget-to-actual comparisons
- Explanations of significant variances
- Program and grant-level financial visibility
- Cash flow forecasting
- Revenue and expense projections
- Financial reforecasting
- Board-ready reporting and financial insights
Most importantly, we help nonprofit leaders understand what the numbers mean—and what decisions they may need to make.
If your organization needs clearer financial reporting or help turning budget information into practical management decisions, Bay Business Group can help.
Click here to schedule a free 30-minute consultation with Bay Business Group and learn how our nonprofit accounting professionals can help keep your organization on track.